Tesla Cybercab Production Pivot: Giga Texas Goes All-In on Autonomous Manufacturing
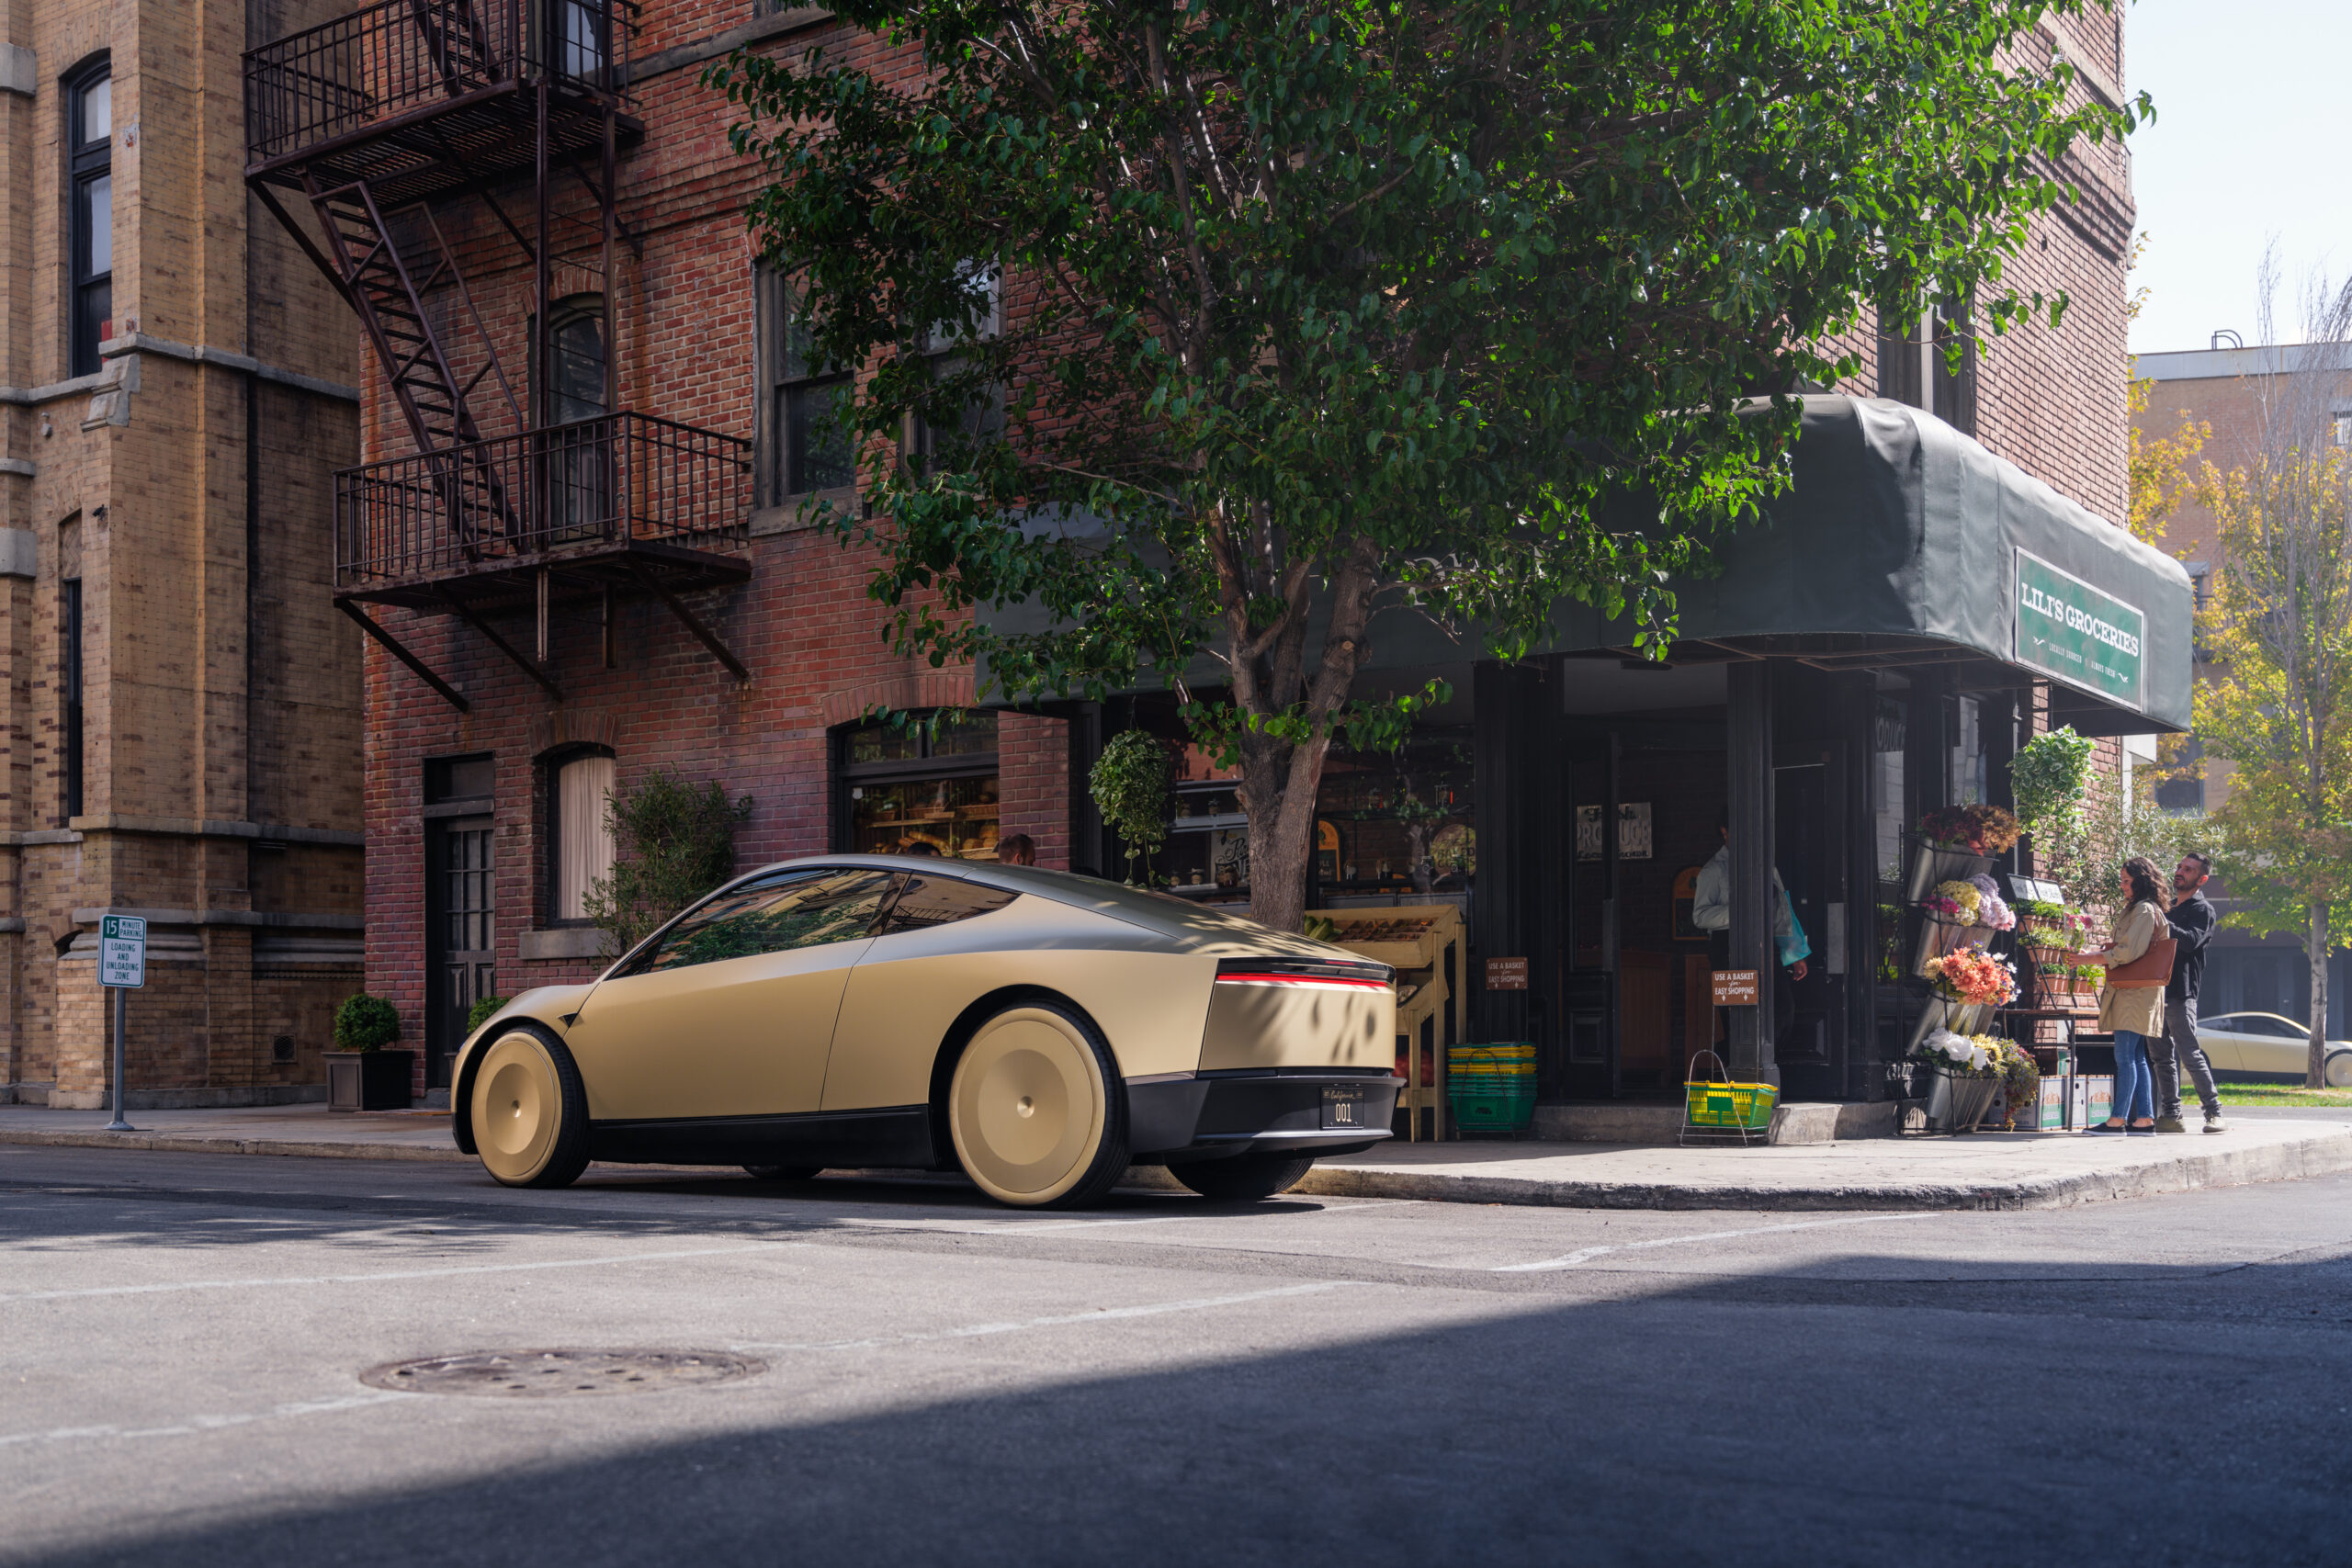
In November 2026, Tesla announced a dramatic manufacturing shift that signals confidence in Cybercab profitability. The company is ending Cybertruck production mid-2027 to reallocate all Giga Texas capacity to Cybercab robotaxi manufacturing. This isn’t a temporary adjustment—it’s a fundamental restructuring of Tesla’s manufacturing strategy that transforms the world’s largest automotive facility into a dedicated autonomous vehicle plant.
The Manufacturing Reality: Why Cybercab Wins Over Cybertruck
The decision to deprioritize Cybertruck—which has consumed over $2 billion in development costs since 2019—reveals Tesla’s true capital allocation priorities. Elon Musk has made explicit that autonomous vehicles represent Tesla’s future, not incremental vehicle variants. The Cybertruck’s delay, production challenges, and mixed market reception pale against the economic logic of Cybercab deployment.
Here’s the math that matters to fleet operators:
- Cybercab target price: $30,000 per unit
- Operating cost: Under $0.30 per mile (Tesla claim)
- Cybertruck retail price: $80,000+ with ongoing production constraints
- Cybercab battery: 48 kWh (optimized for efficiency)
- Cybertruck battery: 100+ kWh (heavy-duty specifications)
Economically, Tesla can manufacture dozens of Cybercabs using the same raw materials and factory floor space as a single Cybertruck. When autonomous capabilities prove reliable at scale, fleet operators will select Cybercabs not out of brand loyalty but because the unit economics are unbeatable.
Giga Texas: From Dual-Purpose to Autonomous Dedicated
Giga Texas has been Tesla’s battleground facility—manufacturing both Cybertruck and Model Y vehicles while serving as the company’s primary robotaxi testing ground. The facility’s size (approximately 10 million square feet) is unmatched globally. Dedicating that entire manufacturing footprint to Cybercab production signals Tesla believes volume demand will justify the pivot.
Current trajectory:
- Current state: Cybercab production began April 2026 at “very slow” initial rates
- Mid-2027: Cybertruck production ends; Giga Texas reallocates 100% capacity to Cybercab
- 2027-2028: Production ramp accelerates as manufacturing processes optimize
- Target capacity: Multiple sources suggest 2 million units annually is Tesla’s long-term goal (per Musk’s prior comments)
For fleet operators, this timeline matters. If Tesla achieves even 500,000 Cybercabs annually by 2028, supply becomes the limiting factor in deployment—not technology or regulatory approval. Early fleet partners who secure vehicles in 2027-2028 will have first-mover advantage before Waymo and competing platforms can scale Chinese-sourced vehicles or Zoox’s custom platforms to competitive volumes.
The 40 kWh Battery: Cost War Intensifies
Tesla is engineering a smaller battery pack (40 kWh) specifically optimized for Cybercab economics. Standard configurations currently use 48 kWh, but the company is pursuing further cost reduction to hit the $30,000 price target at scale. This isn’t a minor spec change—it’s evidence Tesla is aggressively competing on manufacturing cost, not features.
Why this matters:
- Waymo economics: Heavily modified existing vehicles with $50,000+ sensor arrays and labor costs
- Zoox economics: Custom platform with Amazon backing but unproven manufacturing scale
- Cybercab economics: Purpose-built platform with Tesla’s existing gigacasting, battery, and manufacturing expertise
A 40 kWh battery pack, combined with Cybercab’s lightweight design (3,113 lbs), creates a robotaxi with the lowest possible per-mile operating cost in the industry. If Cybercab achieves regulatory approval and proves autonomous capabilities reliably, Waymo’s cost advantage disappears.
Regulatory Uncertainty: The Remaining Wildcard
Tesla’s manufacturing pivot assumes regulatory approval will arrive in a timely manner. NHTSA’s ongoing investigation into Cybercab self-certification and the unresolved question of steering-wheel-free vehicle standards remain critical unknowns.
Best case scenario: NHTSA approves Cybercab deployment in Q4 2026 or Q1 2027, allowing fleet operations to expand beyond Austin’s geofence. Tesla begins customer deliveries to fleet operators in late 2026 as planned. Production ramps in early 2027.
Base case scenario: NHTSA requires formal exemption requests or new regulations to authorize steering-wheel-free vehicles. Process extends to mid-2027. Production continues at slow rates until approval clarifies. Fleet operators wait to commit capital until regulatory pathway is certain.
Worst case scenario: NHTSA rejects self-certification; Tesla must retrofit steering wheels on all vehicles or forfeit U.S. deployment. Giga Texas pivot proceeds anyway but serves international markets only. Production continues but deployment narrows to Europe, Asia, or other regulatory jurisdictions.
Tesla’s manufacturing commitment is a bet that the base or best case unfolds. The company wouldn’t reallocate Giga Texas capacity without internal conviction that regulatory approval arrives within 12-18 months.
The Competitive Landscape: Time as Weapon
Waymo currently operates 1,100+ vehicles in Texas alone, with global fleet exceeding 4,000 units. The company has proven autonomous capability at meaningful scale and demonstrated operational reliability. However, Waymo faces a manufacturing reality: most of its vehicles are modified Chrysler Pacificas, which limits scaling speed and increases per-vehicle costs.
Waymo’s recent decision to order Chinese-built vehicles at scale signals the company recognizes manufacturing costs matter. If Waymo shifts to Chinese platforms, it loses the vehicle cost advantage it currently holds. Tesla, by contrast, manufactures the majority of its components in-house and controls battery supply—giving Cybercab inherent cost structure advantages.
The race is now about who scales autonomous vehicles to 50,000+ units annually first. Waymo’s operational advantage today means nothing if Tesla’s manufacturing advantage enables 10x greater fleet deployment by 2028.
Fleet Operator Implications: The Timing Window
For fleet operators evaluating robotaxi investment, Tesla’s manufacturing pivot sends a signal: this company expects Cybercab adoption to accelerate materially within 12-24 months. If the company is dedicating Giga Texas—its most important facility—to Cybercab production, internal revenue forecasts must justify that capital reallocation.
Fleet operators should expect:
- Price stability: $30,000 target price likely holds through 2027 to drive adoption
- Availability constraints: High demand will outpace initial supply; early commitment now secures 2027 delivery slots
- Operational support: Tesla will prioritize fleet operators over consumer sales initially (higher volume, predictable utilization)
- Regulatory catalysts: NHTSA decision in Q4 2026 or Q1 2027 will be the inflection point for fleet scaling
The manufacturing pivot also signals Tesla expects autonomous capabilities to reach commercial reliability threshold soon. No company reallocates its largest factory without confidence in product-market fit.
What This Means for Your Fleet Economics
If you’re evaluating robotaxi investment, Tesla’s manufacturing commitment reduces execution risk. The company is betting its capital on Cybercab success. When Giga Texas fully transitions to Cybercab production mid-2027, you’re looking at a company with:
- Proven automotive manufacturing expertise at scale
- Lowest-cost production of any autonomous vehicle platform
- Global battery supply chain (critical competitive advantage)
- Existing robotaxi deployment infrastructure in multiple U.S. cities
- Demonstrated commitment to autonomous vehicle strategy (not a side project)
Waymo remains the current operational leader, but Tesla’s manufacturing pivot suggests that advantage is temporary. The company that scales cost-competitive autonomous vehicles to 1 million+ miles annually will dominate fleet operators’ capital allocation in 2028-2030.
The timeline is compressing. If you’re considering Cybercab fleet deployment, the next 6-12 months are decision-making months, not observation months.
Get Ahead of the Robotaxi Market
At Auto Auto, we help fleet operators evaluate autonomous vehicle investment opportunities and model long-term economics. Tesla’s manufacturing pivot changes the calculus for robotaxi ROI. Let’s discuss what Cybercab deployment means for your business.
Contact us: josh@autoautous.com or call 919-389-8290
Fleet deployment decisions made today will determine competitive position in 2028. Let’s talk about your robotaxi strategy.